“Cyclical don’t just go up and then down; it’s that the extreme highs cause the eventual lows, and the lows pave the way for the recovery.” — Howard Marks
From 2012 to 2022, Relaxo was an absolute titan, compounding investor wealth at a massive CAGR, turning a modest footwear business into an unshakeable consumer powerhouse. But, over the last two years, the stock has experienced a brutal correction, tumbling from its historical highs above ₹1,000 down to a sobering ₹331 as mass-market rural consumption slowed down.
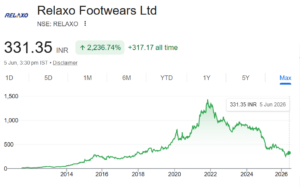
Reason: Poor sales number, lower operating margin and lower profit in last 5 years.
But the recent signs point to a turnaround in the coming months. Below outlines the key attributes of the company:
1.The Moat (Competitive Advantage): Relaxo possesses a strong brand moat in India’s mass-market footwear segment through household names like Flite, Sparx, and Bahamas. Its true structural moat is its massive scale and low-cost manufacturing capabilities, which allow it to maintain profits on products with incredibly low price points.
2.A Fortress Balance Sheet: High Anti-Fragility
A hallmark of every sustainable multi-bagger is financial self-sufficiency. Relaxo operates an asset-heavy manufacturing footprint with virtually zero net debt. In an era where volatile economic shifts eat away at corporate profitability, Relaxo’s balance sheet acts as a solid shield. With a Debt-to-Equity ratio of ~0.01, Relaxo possesses extreme anti-fragility. It can absorb raw material price shocks and economic cycles that easily wipe out weaker, unorganized competitors.
3.Financial Performance & Valuation Reality Check
Skeptics point out that Relaxo’s topline has temporarily stagnated due to pressure on rural disposable incomes. However, true fundamental analysis looks at the underlying core profitability trends. As shown below, the margin recovery engine has already fired up:
| Metric | FY24 | FY25 | FY26 | Trend Analysis |
| Revenue (Cr) | ₹2,914.06 | ₹2,816.57 | ₹2,748.36 | Topline Stagnation: Revenue fell 1.5% in the last year, reflecting persistent stress in rural/mass-market consumption and local unorganized competition. |
| Net Income (Cr) | ₹200.47 | ₹170.33 | ₹179.27 | Margin Recovery: Despite lower revenue, net profit rose 5.3% in FY26. This was driven by cost optimizations and stabilizing raw material (EVA/Rubber) prices. |
| EPS (₹) | ₹8.05 | ₹6.84 | ₹7.20 | Rebounding slightly from the FY25 bottom, but still below FY24 peaks. |
| Q4 FY26 PAT (Cr) | — | ₹56.22 | ₹67.67 | The Bright Spot: Q4 net profit surged 20.4% YoY, driven by volume growth and trade channel recovery. |
From a valuation standpoint, Relaxo’s historical P/E often crossed an astronomical 80x. Today, at a trailing P/E of ~46x to 52x, the market has violently priced in the slowdown. For a business with an unshakeable market moat and 18%+ historical Return on Capital Employed (ROCE), this correction provides long-term investors with a high Margin of Safety.
3. The Operational Inflection Point: Q4 Outperformance
The absolute validation of a turnaround is visible in the quarterly run rate. While full-year revenue looked soft, Q4 FY26 results delivered a massive positive surprise. Driven by stabilizing raw material costs (EVA and rubber) and channel de-stocking coming to an end, profitability broke free from the revenue shackles.
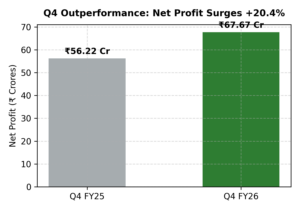
A 20.4% YoY surge in quarterly net profit indicates that the worst of the margin contraction is definitively over.
From a valuation standpoint, Relaxo’s historical P/E often crossed an astronomical 80x. Today, at a trailing P/E of ~46x to 52x, the market has violently priced in the slowdown. For a business with a strong market moat and 18%+ historical Return on Capital Employed (ROCE), this correction provides long-term investors with a high Margin of Safety.
Relaxo is a classic example of a “good business hitting a temporary patch.” The company’s intrinsic brand strength remains perfectly intact. When rural demand revives , full operational leverage will kick in on an already optimized cost structure. Do not wait for the volumes to print 15% growth before buying; by then, the stock multiple will scale back to 80x.
Very well researched and beautifully summarised
Thoroughly researched and very well put article Nitesh